
Medicare drug coverage
Is the Medicare Drug Plan With the Lowest Premium Always the Cheapest?
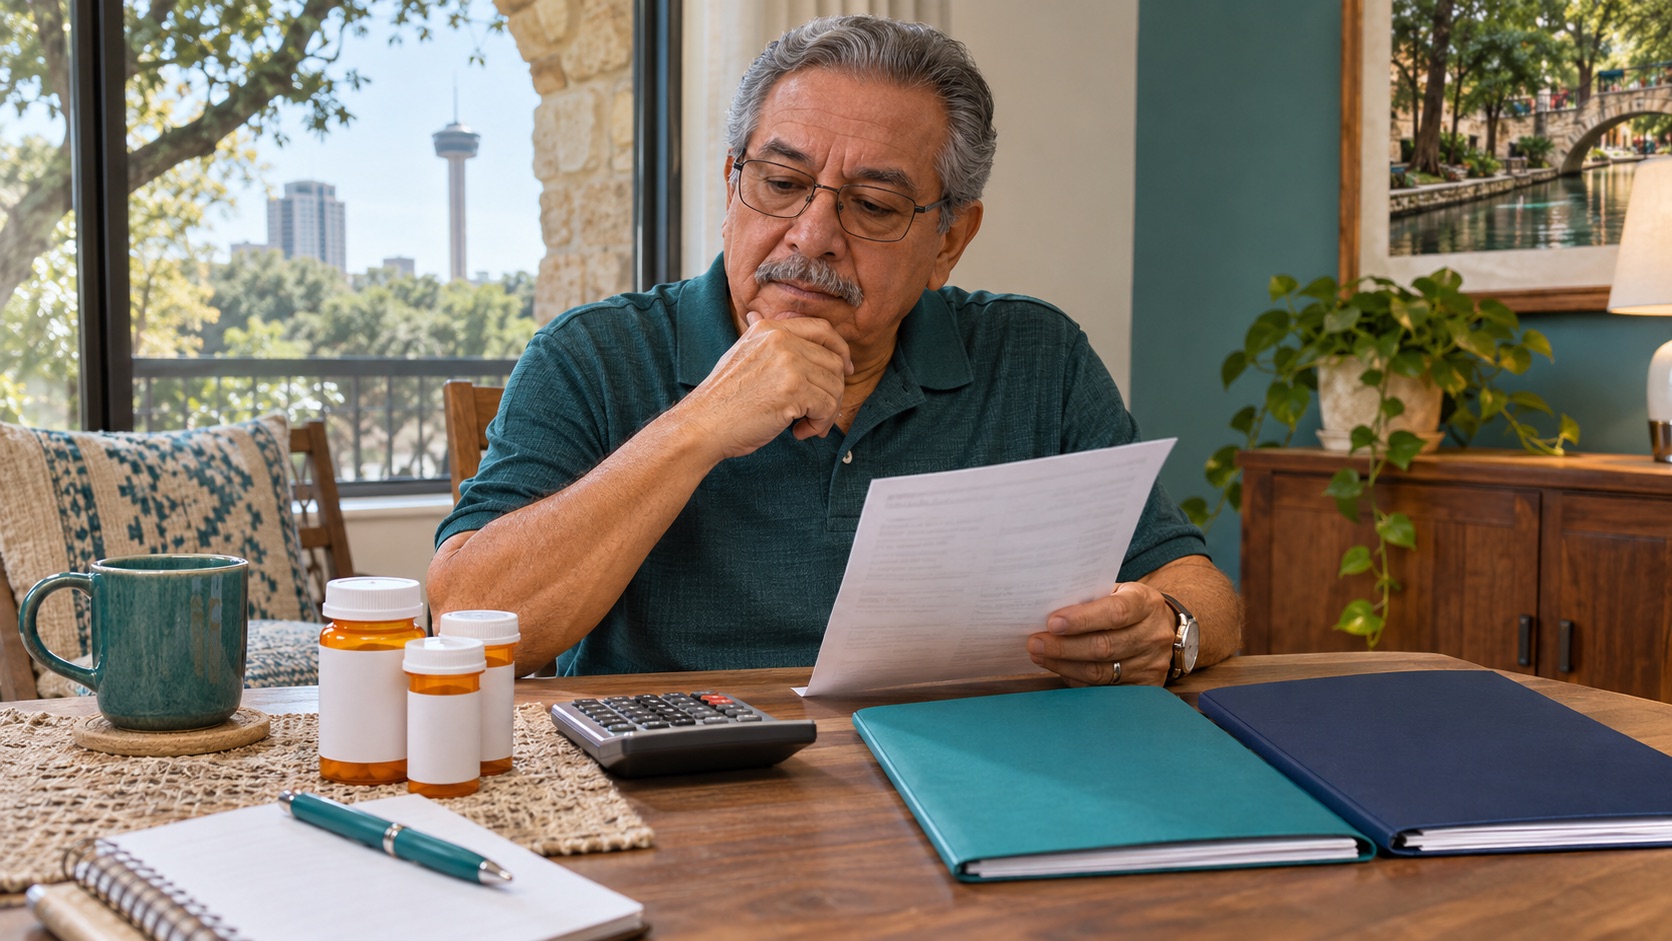
No. A Medicare drug plan with a low monthly premium may still cost more overall once you include prescription expenses. Compare your actual medications, pharmacy, deductible, and copayments or coinsurance before deciding.
The monthly premium is easy to notice. What you pay when filling prescriptions deserves just as much attention.
WHAT SHOULD I COMPARE BESIDES THE PREMIUM?
Look at how each plan covers the medications you take and what your estimated costs may be throughout the year.
Important details include:
- Whether your medications are covered.
- Your deductible and when it applies.
- Copayments or coinsurance for your prescriptions.
- Your pharmacy’s participation and pricing.
- Coverage requirements or restrictions.
- Your estimated total annual costs.
A plan that works well for a friend may work differently for you because your prescriptions and pharmacy are different.
WHAT INFORMATION SHOULD I BRING TO A PLAN REVIEW?
Bring an updated medication list and the names of the pharmacies you use.
For each prescription, include the exact name, strength, dosage form, quantity, and how often you refill it. Prescription labels can help you provide accurate information.
Also mention whether you use mail order or have difficulty traveling to a pharmacy.
Accurate details make the comparison more useful. An outdated medication list can lead to an estimate that does not reflect your needs.
WHAT IS A FORMULARY?
A formulary is the plan’s list of covered medications.
Plans may place medications into different cost-sharing tiers. Some prescriptions also have requirements such as prior authorization, quantity limits, or trying another medication first.
If a medication has a restriction, ask what that means before enrolling. Do not assume that a listed medication will be available without additional steps.
Your prescriber should handle medical questions about alternatives or changes to treatment. An insurance review does not replace that advice.
WHY SHOULD I LOOK AT YEARLY COSTS AND MONTHLY EXPENSES?
Both matter because you need to understand the overall estimate and when you may face expenses.
For example, Robert, a fictional Medicare beneficiary in San Antonio, prefers a plan with a lower premium. After comparing his prescriptions, he learns that another option may have lower estimated total costs.
He also reviews what he might pay early in the year. That helps him consider both his yearly budget and his monthly cash flow.
Estimates are not guarantees. Costs can change if your medications, usage, or other circumstances change.
WHAT IF I AM COMPARING MEDICARE ADVANTAGE PLANS?
Prescription coverage is only part of that decision.
You should also review medical benefits, provider networks, and out-of-pocket costs. A favorable prescription estimate does not tell you whether the plan meets your other healthcare needs.
FREQUENTLY ASKED QUESTIONS
Does a $0 premium mean my prescriptions are free?
No. A plan may still have deductibles, copayments, or coinsurance.
Should I review coverage if my prescriptions have not changed?
Yes. Plan coverage and costs may change.
Can I switch medications to save money?
Discuss that with your prescriber. Do not change or stop medication based only on an insurance comparison.
WANT HELP COMPARING YOUR MEDICARE OPTIONS?
Simply Health Insurance Agency can help you understand prescription coverage and the questions to ask before choosing a plan.
Website: simplyhealthinsurance.net Email: [email protected] Call or text: 210-239-3151